

TLDR: Temporal is a $5 billion AI infrastructure company that ensures AI agents and complex software workflows never lose their place when something goes wrong - think of it as the reliability layer the entire AI industry is quietly building on top of. Founded by two engineers who spent 15 years solving this exact problem at Amazon, Microsoft, and Uber, the company crossed $100M in annual revenue in January 2026 growing at 380% year over year, with existing customers expanding their spend by 184% annually. This post breaks down the business, the metrics, the risks, and whether the infrastructure playbook that built Cisco, Stripe, and Datadog into generational companies applies here too.
Every major technology wave has been won by a company nobody saw coming.
The internet era produced Cisco - not Amazon, not Google, not any of the websites people actually used. Cisco built the routers. The routers moved the data. The data made everything else possible. By the time most people understood what Cisco did, it was briefly the most valuable company on earth.
The cloud era was won by AWS and VMware. Not Salesforce, not Dropbox, not the thousands of SaaS applications that ran on top. The infrastructure won.
We are in the early innings of the AI era. Everyone is watching OpenAI, Anthropic, and Google fight over foundation models. Nvidia sells GPUs. Hundreds of AI startups raise hundreds of millions to build applications on top of models that improve every six months.
And in a 400-person office in Seattle, a company called Temporal Technologies is quietly building the infrastructure layer that serious investors believe could matter more than most of the above.
Temporal raised $300 million in February 2026 at a $5 billion valuation, led by Andreessen Horowitz with participation from Sequoia, Lightspeed, Tiger Global, and GIC. It crossed $100 million in ARR in January, growing at 380%(!) year over year. Its Net Dollar Retention is 184%(!). These are not small numbers, and they are not coming from a company operating in obscurity - a16z published a full investment memo explaining exactly why they wrote the check. This post is an attempt to work through that thesis, add some analytical context, and explain why the business behind these metrics is genuinely interesting.
The Problem
Modern software is not one thing running in one place. It is dozens of services, APIs, and databases running simultaneously across distributed cloud infrastructure, talking to each other constantly, each with its own availability characteristics and failure modes.
When you place a DoorDash order, that single tap on your phone triggers somewhere between 15 and 50 separate steps. Charge the card, check restaurant availability, notify the driver, update inventory, send the confirmation, calculate the delivery time, update loyalty points. Each step talks to a different system. Each system has its own bad days.
When one of those systems fails halfway through - and they do, regularly - something has to decide what happened, what still needs to happen, and how to make sure the transaction completes correctly and only once. Historically, that something was the engineers who built the system, writing what developers call infrastructure code - retry logic, timeout handlers, state management, error recovery. None of it is the product. All of it is plumbing. And it consumes, by most estimates, more than 70% of engineering time that could have been spent on features customers actually care about.
The problem becomes significantly worse with AI agents. An AI agent is not a simple request-response interaction. It is a long-running process that makes decisions and tool calls. It’s searching the web, calling APIs, writing files, generating code, and all of this over an extended period of time. When the server restarts mid-task, when the external API times out, when the network drops for three seconds, the agent loses its place. It either crashes or starts over. Burning time, money, and in the case of language model inference, significant compute costs.
This is not an AI model problem. The models are fine. It is a software infrastructure problem, and it is as old as distributed computing.
“What Does Temporal Do?”
Temporal’s solution is called durable execution, and the core idea is straightforward even if the implementation is not.
When you build on Temporal, the platform records every step of your workflow in real time - an immutable log of everything your code has done, every variable, every state transition. If the server crashes between step seven and step eight of a fifteen-step process, Temporal automatically reconstructs the entire execution state on a different server and resumes at step eight. The developer writes no recovery code. The application behaves as though the failure never happened.
“You build your application as if failures don’t exist,” co-founder Maxim Fateev explained in a recent interview, “because for your application, they don’t.”
Netflix adopted Temporal in 2021 to manage their deployment infrastructure. Before adoption, 4% of deployments failed due to transient infrastructure issues - errors unrelated to the code being deployed, simply the chaos of operating at scale. After Temporal, that figure dropped to 0.0001%!! Netflix published that number on their engineering blog in December 2025. The improvement is four and a half orders of magnitude.
Every Snapchat story runs through a Temporal workflow, including the spike of millions posted simultaneously on New Year’s Eve. Every Taco Bell mobile order is a Temporal workflow. Before Temporal, Yum Brands’ biggest technical stress test was the Super Bowl. After migration, every Taco Tuesday exceeded Super Bowl volume, because the technical ceiling that had been quietly capping their marketing ambition was removed. OpenAI’s Codex agent (the one that writes and executes code autonomously in the background), runs on Temporal, handling millions of executions across complex multi-step tasks.
The customer list reads like a who’s who of engineering-led companies: Netflix, Snap, Datadog, Stripe, Coinbase, Nvidia, ADP. These organizations do not adopt infrastructure tools casually. The evaluation cycles are long, the security reviews are exhaustive, and the switching costs once embedded are significant. That context matters when reading the retention metrics.
The Founders
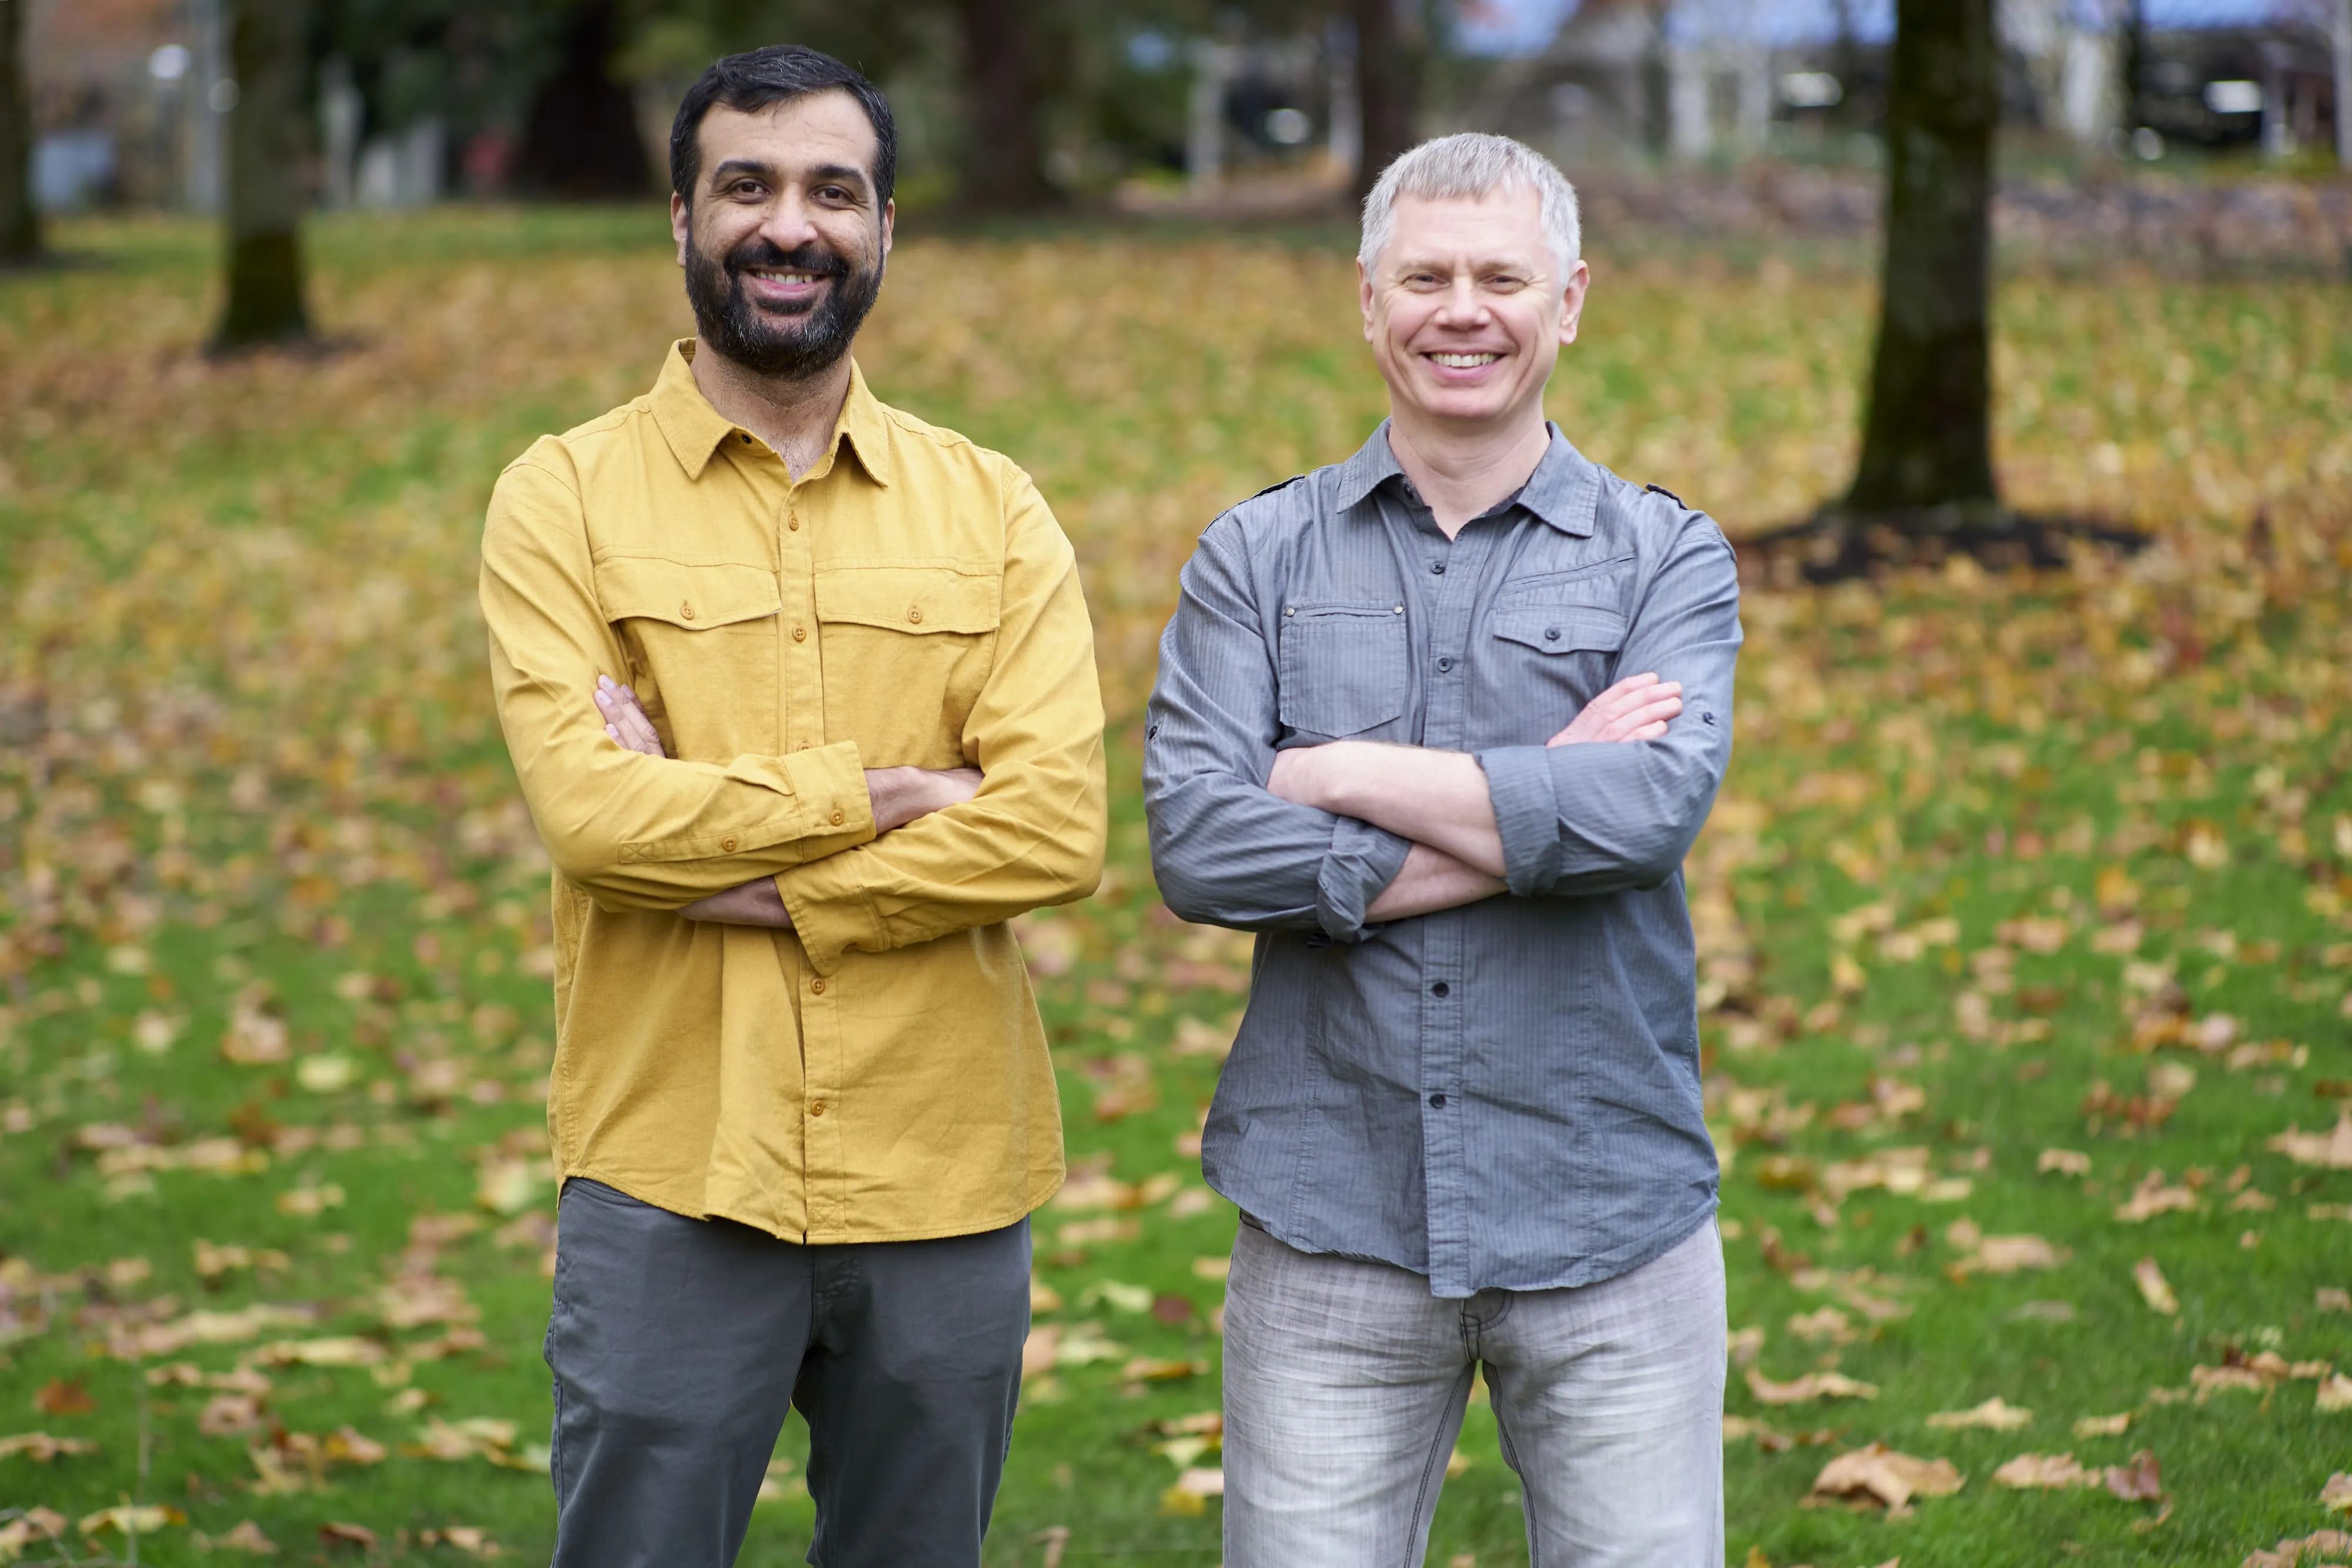
Samar Abbas and Maxim Fateev have been working on this specific problem, in one form or another, since 2010.
Max spent eight and a half years at Amazon, where he was technical lead for the team that built the core infrastructure behind the Simple Queue Service. This is the messaging backbone AWS still runs on today. He later helped build Amazon’s Simple Workflow Service, an early attempt at solving distributed systems reliability at cloud scale.
Samar started at Microsoft, spent a decade across developer platforms and server products, then joined Max on the Simple Workflow team at AWS. Returning to Microsoft, he started an open-source project called the Durable Task Framework, where he started implementing the same ideas for the Azure ecosystem. It gained enough organic adoption that Azure Functions eventually took a dependency on it, shipping it as Azure Durable Functions.
Both of them, by coincidence, joined Uber’s Seattle office within a month of each other in 2015. Uber was navigating the consequences of extremely fast growth. They had more microservices than engineers, and building any stateful application required orchestrating calls across dozens of systems simultaneously. Max and Samar built Cadence, an internal open-source platform for solving exactly this. Within three years it was running over 100 applications inside Uber. External companies started adopting it without being asked — Airbnb, HashiCorp, Box, Coinbase.
In 2019 they forked Cadence, named it Temporal, and started a company. The transition from open-source project to commercial product was unusual in that genuine enterprise demand existed before the company did. Sequoia led the Series A. The thesis was straightforward: two engineers who had built this product multiple times, at the most demanding engineering organizations in the world, with proven external adoption before a single sales hire.
The Business Model
Temporal’s commercial product is Temporal Cloud - a fully managed version of the platform where customers pay based on consumption rather than seats. The more workflows they run, the more they pay. It is a model that aligns incentives cleanly: Temporal’s revenue grows when customers’ applications grow, which means the sales team is structurally incentivized to help customers succeed rather than close deals that sit unused.
“Our salespeople are compensated on consumption,” Samar explained in a podcast interview. “They make money when customers are actually using the product. It creates very good alignment.” In internal surveys where customers ranked different parts of the organization they interact with, Temporal’s sales team scored highest — above engineering and support. That is unusual enough to be worth noting.
The consumption model also explains the Net Dollar Retention of 184%. As customers build more applications on Temporal, as those applications handle more traffic, as AI agents run more executions, the revenue from that customer grows automatically. There is no renewal negotiation, no upsell pitch. The number goes up because the product is embedded in systems that are themselves growing.
184% NRR means the existing customer base, without any new logos, would nearly double revenue annually. Snowflake at its peak reported around 170%. The metric is important because it tells you something about the quality of the product and the depth of the integration — customers do not expand usage of infrastructure they are indifferent to.
The open-source strategy reinforces the commercial flywheel. Temporal’s core platform is MIT licensed — fully open, free to self-host, no enterprise licensing restrictions. This is deliberate. It means engineers can evaluate, adopt, and build on Temporal without procurement involvement, without legal review, without a sales conversation. By the time the organization wants the managed cloud service, the engineers are already committed. The platform had 183,000 weekly active open-source developers and 20 million monthly installs as of the Series D announcement. This kind of distribution moat is genuinely difficult to replicate.
The AI Timing
Temporal was not built for AI agents. It was built for distributed systems reliability broadly — payments, e-commerce, deployments, loyalty programs. The agentic AI wave arrived and discovered that the infrastructure problem it needed solved had a fifteen-year-old solution.
The timing is notable because the demand acceleration appears structural rather than cyclical. AI agents are long-running, non-deterministic processes that orchestrate calls across multiple external services. They are precisely the class of application that breaks traditional infrastructure and benefits most from durable execution. As enterprises move from AI pilots to production deployments. This is a transition that is visibly accelerating in 2026. The reliability layer underneath those deployments becomes critical infrastructure.
“Agentic AI doesn’t fail because the models aren’t good enough,” Samar said at the Series D announcement. “It fails because the systems around them can’t handle real-world execution.”
The $650 billion in AI infrastructure capex committed by hyperscalers in 2026 will produce a wave of production AI deployments. Each one of those deployments needs what Temporal provides. The company did not engineer this timing — it is simply the consequence of building the right product and waiting long enough for the market to arrive.
The Valuation
At $5 billion on $100 million of current ARR, Temporal trades at 50x. That is an expensive multiple by any conventional measure, and it is worth being direct about that rather than engineering around it.
But the conventional measure is the wrong frame. Dividing the current multiple by the current growth rate gives a growth-adjusted multiple of 0.13x. When we compare this to a peer median of 0.45x across Datadog, Confluent, Cloudflare, and MongoDB, it doesn’t look very expensive anymore. Even acknowledging that 380% growth will not sustain indefinitely, the gap is wide enough that Temporal looks cheap relative to its peers on almost any reasonable deceleration scenario.
The NRR provides a harder floor. With existing customers expanding at 184% annually, the base alone generates close to $184 million in the next twelve months before a single new logo is added. Factor in active expansion into EMEA and Asia Pacific against an AI agent tailwind that is still accelerating, and a forward ARR of $300 million or more is a reasonable working assumption for full year 2026 — implying roughly 17x forward revenue, below where Datadog and Cloudflare traded at equivalent growth stages before becoming significantly larger companies.
The multiple is only justified if the growth is durable. The bear case is straightforward: 380% was a one-time spike driven by the AI wave hitting in 2025, growth decelerates sharply as the base gets larger, and the valuation resets accordingly. That is a legitimate risk and anyone presenting this as a certain outcome is being intellectually dishonest.
The bull case is that the AI agent wave is still in its earliest stages, as Samar Abbas put it, in the “MS-DOS era of agents” and that Temporal’s consumption-based model means revenue scales automatically as AI deployments grow without a single additional sales hire. Every enterprise that moves an AI agent from pilot to production is a potential expansion in Temporal’s revenue base. At $5 billion today, if the trajectory even loosely resembles what Datadog and Cloudflare looked like at this stage, the entry point looks reasonable in hindsight.
The valuation demands execution. The NRR suggests the product is already delivering it.
The Risks
Cloud giant competition. AWS Step Functions, Google Cloud Workflows, and Azure Durable Functions are all competing products offered free or at low cost within their respective ecosystems. For smaller organizations running single-cloud architectures with straightforward workflow needs, these tools are often sufficient. This is a real ceiling on Temporal’s addressable market, particularly in the SMB segment.
The structural counter-argument is that enterprises running multi-cloud architectures (the majority of the Fortune 500) cannot use AWS Step Functions as a cross-cloud execution layer. The complexity of production AI agent workflows also tends to exceed what bundled tools handle well, as the engineering community has discovered through experience rather than marketing. The Temporal community forum has extensive documentation of teams migrating from Step Functions to Temporal specifically because Step Functions broke under the complexity of their use cases.
Adoption friction. Temporal requires engineers to adopt a new programming model, a deterministic workflow code. That has a real learning curve. The platform’s own documentation is candid about this. Teams that adopt it without sufficient engineering maturity struggle. This slows enterprise sales cycles and limits the bottom-up adoption story in less technical organizations.
In practice this appears to be a market segmentation feature rather than a fundamental weakness. The customers who successfully adopt Temporal tend to be sophisticated engineering organizations with complex enough problems to justify the investment — and those are precisely the customers who produce 184% NRR rather than churning.
Valuation execution risk. At 50x current ARR, there is limited margin for error. A meaningful deceleration in growth or a deterioration in NRR would compress the multiple significantly. The company has raised $650 million in total funding, which provides substantial runway, but the expectations embedded in the current valuation require sustained exceptional performance.
My Honest Conclusion
Temporal is not a hidden gem, it has a16z, Sequoia, Lightspeed, and GIC on the cap table, and a Series D at $5 billion is not obscure by any definition. It is a well-capitalized, well-regarded infrastructure company with genuinely exceptional operating metrics, a structural tailwind from the AI agent wave, and founders whose domain expertise in this specific problem is as deep as you will find anywhere in the industry.
Whether it becomes a $100 billion company depends on execution, on how quickly enterprise AI deployments scale, and on whether the cloud giants develop competing solutions that are genuinely good enough to displace it in the enterprise segment. None of those outcomes are certain in either direction.
What the evidence does support is that the problem Temporal solves is becoming more important, not less. That every serious AI deployment in production eventually encounters the reliability problem that Temporal exists to fix, and that the business metrics suggest the product is delivering on its promise at scale. A $100 billion outcome requires a lot of things to go right. But the foundation being built looks like the kind that serious infrastructure companies are built on.
The infrastructure layer has a way of mattering more than it looks like it will, early on. It did in the internet era. It did in the cloud era. The AI era is unlikely to be different.
Temporal Technologies is a private company. This post represents the author’s personal analysis and opinions and is not financial or investment advice.